

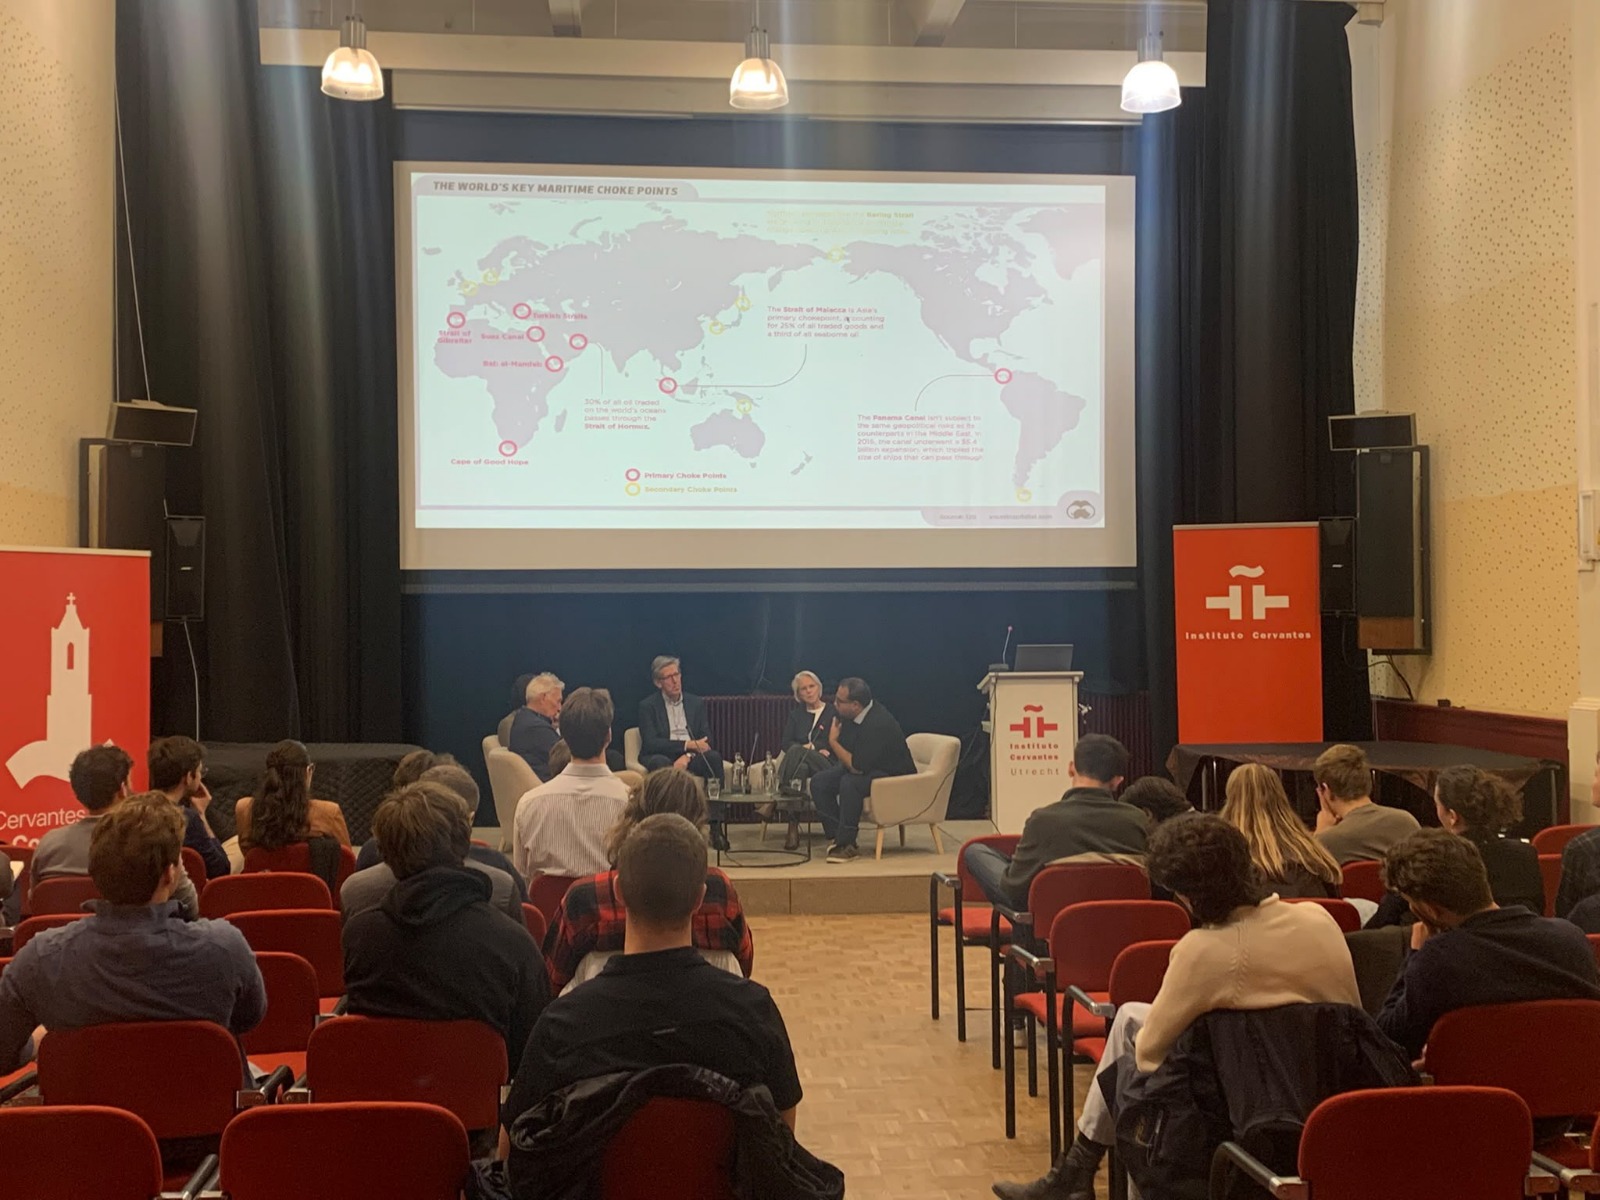
This month, we had our very first Member’s Insight Night with Research Fellow Midas van de Weetering. For his thesis, he investigated the Financial Crisis of 1763 which is by many researcher considered to be the first international banking crisis. We investigated this crisis from an IR perspective, focusing on the geopolitical side of things.
The crisis of 1763
But first, a historical overview of the crisis is needed to explain the intricacies of this financial predicament. During the 18th century, the bankers in Amsterdam played a vital role in the flourishing international economy. With the VOC as the first publicly traded company, great access to transport routes and plenty of capital available, these merchant bankers were able to make investments on a gigantic scale, something unthinkable a few centuries earlier, and amass large capital in the process.
The Dutch bankers also benefitted immensely from the 7 Year War, where the factions of Prussia and Great Britain warred against France, Saxony, Spain, Russia and Sweden with battle fields taking place both in Europe and the Americas. This war, in which the Dutch Republic remained neutral, created an amazing business opportunity for the merchant bankers in Amsterdam. Prices of goods soared as international trade was severely hampered by the war. As demand only got greater while shortages further amplified, Dutch bankers were able to obtain huge profits through speculation and credit.
These insane profits halted abruptly with the Treaty of Paris in 1763, where peace was brokered between the warring parties. This created an steep fall in prices, leading to a collapse of the international banking system. Bankers had been making increasingly risky investments, and when de Neufville, one of Amsterdam’s biggest bankers, declared himself bankrupt after a failed investment in grain, it started a disastrous chain reaction of bankruptcies of the biggest bankers. Nobody could pay back their loans making the ‘wisselbrieven’, which was the most commonly used method of investment, essentially worthless.
The geopolitics of the crisis
First, we can distinguish classic small state behaviour. The neutrality of the Dutch Republic created many trade opportunities of its merchant bankers; remaining neutral was thus a choice made out of self-interest. The financial activities, like speculating on goods like gun powder or grain, are thus completely intertwined with the war activities. These bankers also correctly assessed that the likes of Prussia and Sweden would adopt an inflationary monetary policy where they minted new coins with a higher percentage of iron rather than gold and silver. The Dutch bankers invested heavily in gold, which was needed for the minting process, and also negotiated favourable contracts with the old coins as payments; these were worth significantly more than the new coins, making it easier to pay of contracts with their currency reserves.
When we look at the aftermath of the crisis, we again see multiple political influences at play. Frederick the Great, king of Prussia and the oligarchs of Hamburg demanded that the Amsterdam merchant bankers bailed out de Neufville.

A letter in which Hamburg bankers request the Dutch to save de Neufville.
De Neufville was good friends with these traders as he had tried to create a similar trade and banking hub in current day Germany. This plan was not welcomed by the other Amsterdam bankers, as it brought additional competition, and they therefore refused to bail him out. In response, Hamburg froze trade with the Dutch, eventually declaring mass bankruptcy as the Dutch violated their contracts, refusing to pay back their debt.

Bankruptcies in both Amsterdam and Hamburg in 1973
Interestingly, each state and city had their own crisis policies. There was no international system to coordinate an common response; there was nearly no cooperation at all. A quote from a banker who reflects on the crisis encapsulates the zeitgeist at the time:
“There was one thought guiding us in 1763, if someone must suffer, let it be the foreigner“
Amsterdam suffered relatively mildly as their financial markets were rather mature, allowing them to bounce back. Even though they moderately recovered, the Dutch bankers did not send any aid to other states or cities.
When we look at the greater picture, a form of Finaical Realpolitik can be distinguished:
- There were unequal power relations
- Actions were perpetrated out of self-interest
- International non-cooperation due to a lack of institutions and regulatory bodies
Parallels to contemporary crises
When we looked at the 2008 crises, we see certain similarities. First, the investments of bankers got too risky. Whereas bankers from the Dutch Republic tried to offset risky ‘wisselbrieven’ with more stable ones, the 2008 bankers compensated for high-risk-high-reward contracts (debt and mortgage) by bundling them together with safer investments in private equity.
Moreover, in both instances there was a lack of regulation. Even though we have watchdog organisation like the IMF, a lot of deregulatory policies had been implemented in the banking sector, for example with Reaganomics. Nobody stepped in to prevent the financial sector from making these risky investments, essentially creating a bubble through debt-cycle which was bound to burst.
The important difference is that the 21-st Century bankers knew that they would be bailed out as they were essentially too big to fail. If they weren’t saved by the government, society as we know would collapse. This is also why AIG was saved but Lehman Brothers was not: AIG was deemed instrumental to society as they were too ingrained both on a political and societal level, while Lehman was not despite their economic prowess.
The main takeaway from these cases is that we need solid regulatory bodies on an international level who can sound the alarm when things are threatening to go wrong. While the financial sector needs sort of autonomy to function, they should not be allowed to throw the entire world into a scramble because of their excessively risky investments. We do not want to repeat the realpolitik of 1763; in our globalised world, we need to cooperate with each other to remain financially healthy.


Leave a Reply